Difference Between Equity Share and Preference Share
- Updated: 12 Oct 2026, 6:18 PM IST
- | 6 min
- 1,040
 Add Preferred News Source
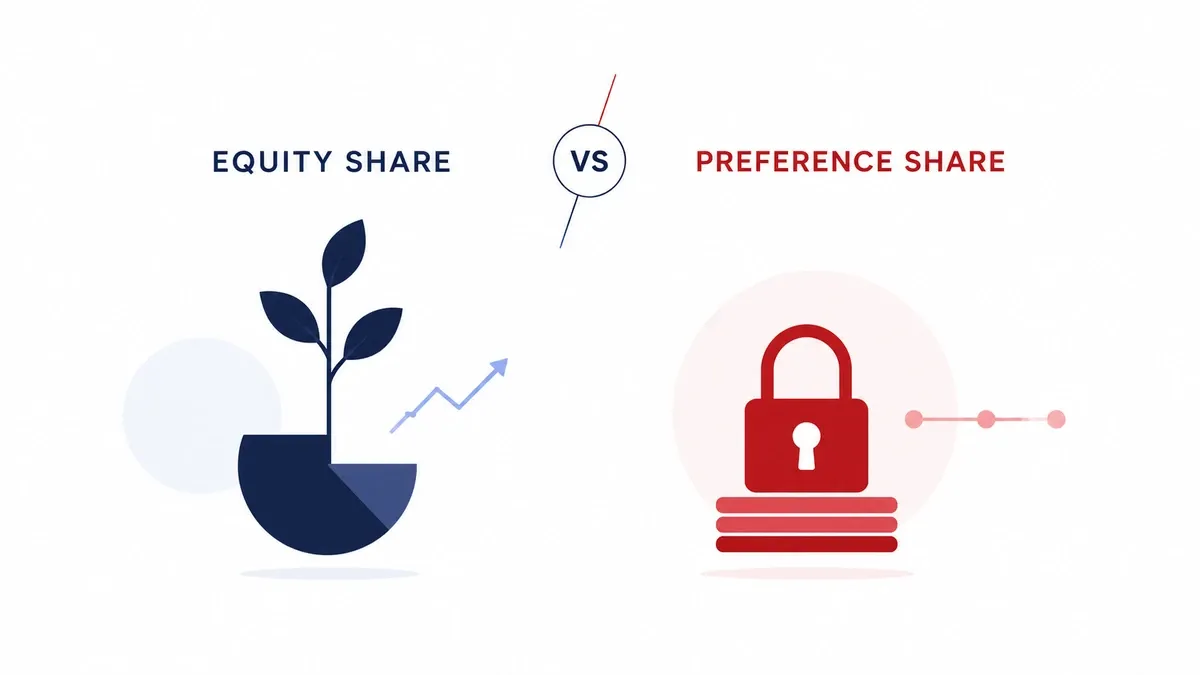
The core difference between equity shares and preference shares is ownership versus priority. Equity shares give you ownership in the company, with voting rights and a share in its profits and growth, but no guaranteed returns. Preference shares give you a fixed dividend and priority over equity shareholders in payouts, but usually no voting rights and limited scope for capital gains.
For a company, equity shares are a way to raise money from owners who share the business risk, while preference shares raise money from investors who want steadier income. For an investor, the choice comes down to whether you want higher growth potential or more predictable returns. Ownership, payouts and risk all differ between the two, so it helps to look at each side by side.
What is an Equity Share?
Equity shares are the regular shares a company sells on the stock market to raise money. Buying one makes you a part-owner of that business, so your returns depend on how well it performs.
If the company does well over the years, your investment can become more valuable, and you may earn dividends along the way, though there is never a guarantee. The risk runs both ways: if profits shrink, the business struggles or investors lose faith, the value of your shares can fall just as fast.
What is a Preference Share?
Preference shares are shares that give investors priority over equity shareholders in dividend payments and in the repayment of capital if the company is wound up. They usually pay a fixed dividend and carry no voting rights.
They are less common than equity shares, but they serve a clear purpose. Instead of aiming mainly for growth, they offer investors a more predictable return. When a company distributes profits, preference shareholders are usually paid first, before equity shareholders receive anything.
The same order applies if the company is wound up. Remaining assets go to preference shareholders first, and equity shareholders are paid only after that.
This priority comes with a trade-off. Preference shareholders get greater security, but equity shareholders have the stronger upside if the company grows substantially.
Difference Between Equity Share and Preference Share
To understand the difference between equity and preference shares, you need to look at how corporate cash flows move through an organisation. They serve two completely different types of market participants.
Equity shares form the true risk-bearing backbone of a company's balance sheet. When you buy ordinary equity, you take on maximum financial risk because your returns are entirely dependent on how well the company performs.
Suppose you invest in the equity shares of a fast-growing technology company. If profits double in the next few years, its share price and dividend payouts could rise sharply. However, if the company records losses, you could receive no dividend at all, and the market value of your investment may fall.
Preference shares are subject to a strictly structured regime. They trade off the substantial potential for profit from capital appreciation for the assurance of a stable income stream. In other words, once a company decides to distribute the profits, preference shareholders are paid their fixed dividend fully before the ordinary shareholders receive any amount.
For instance, if the same company has issued 8% preference shares, preference shareholders are entitled to receive their fixed 8% dividend before any dividend is distributed to equity shareholders. Even if profits are lower than expected, their payment takes priority whenever dividends are declared.
The structural variations between equity and preference shares are detailed in the comparison table below.
Comparison Parameter | Equity Share Class | Preference Share Class |
|---|---|---|
Dividend Rate Status | Fluctuates based entirely on annual net earnings and board choices. | Remains fixed at a contractually pre-determined percentage rate. |
Payment Priority | Handled last, utilising whatever residual profits remain. | Paid first, taking absolute priority over ordinary equity. |
Voting Privileges | Offers full voting rights on key corporate and board resolutions. | Carries zero voting power under normal business conditions. |
Arrears Accumulation | Unpaid dividends disappear completely; they never roll over. | Skipped payouts can accumulate as cumulative arrears. |
Capital Redemption | Permanent capital; the company cannot redeem it during its lifespan. | Can be issued with a fixed maturity date for capital redemption. |
Bonus Share Access | Fully eligible to receive free bonus shares during stock splits. | Holds zero eligibility for corporate bonus share allocations. |
Equity Shares vs Preference Shares: Which is Better?
People often ask this question, hoping for a straightforward answer. Unfortunately, investing does not work that way.
A 25-year-old who has just started earning may happily accept short-term market swings if the investment has the potential to grow significantly over the next couple of decades. For someone like that, equity shares often make more sense.
Now, think about a retired investor. That person may not be interested in waiting years for the share price to appreciate. Receiving relatively stable dividend income could matter much more. Preference shares are often better aligned with that goal.
There's another angle worth considering. Some investors do not choose one over the other. They use both. The table below illustrates how these choices align with specific investment goals.
Investment Goal | Equity Share Approach | Preference Share Approach |
|---|---|---|
Aggressive Wealth Growth | Ideal; captures full capital appreciation as the business expands. | Poor; stock price gains are limited by the fixed nature of the asset. |
Consistent Cash Yield | Unreliable; payouts can be cut or skipped during economic downturns. | Excellent; delivers a reliable, fixed yield regardless of minor profit dips. |
Inflation Protection | High; corporate earnings and asset values naturally scale with inflation. | Low; fixed payouts lose real purchasing power as living costs rise. |
Example of Equity Share vs Preference Share
To see how these equity shares and preference shares work under real corporate conditions, let us look at a consumer electronics company that experiences shifting financial fortunes over three consecutive years. Suppose an investor holds ordinary equity shares in this firm, while another holds an issue of 7% cumulative preference shares.
The table below traces exactly how much cash moves to each investor based on the company's annual financial performance.
Corporate Performance | Payout to Equity Shareholder | Payout to Preference Shareholder |
|---|---|---|
Year 1: Profits Surge 50% | The board rewards investors by raising the equity dividend to 12%. | The investor receives exactly their fixed 7% contract rate. |
Year 2: Supply Chain Crash | Net profits hit zero; the equity dividend is cancelled immediately. | Cash payout hits zero, but the 7% claim rolls over as a corporate debt. |
Year 3: Financial Turnaround | Receives a modest 3% dividend after the preference back-pay is cleared. | Receives a 14% total payout, covering Year 2 arrears plus Year 3 dividend. |
Dividend Rights: Equity Shares vs Preference Shares
This is probably the biggest difference between equity and preference shares. Equity shareholders possess discretionary residual rights. This means they are only paid at the absolute discretion of the board of directors, after all operating expenses, interest payments, taxes, and preference claims are settled. So, if a firm wants to hoard cash to expand, equity holders get nothing, and they have no legal grounds to complain.
Preference shareholders hold a legally protected priority claim on company profits. If a corporation decides to hand out even a tiny fraction of its earnings to owners, preference holders must be satisfied first. Furthermore, if you hold cumulative preference shares, any skipped dividend payments act like a corporate financial liability. The company cannot pay a single paisa to ordinary equity holders in future years until all past preference dividend arrears are paid off in full.
Dividend Attribute | Equity Share Class | Preference Share Class |
|---|---|---|
Distribution Consistency | Highly variable and completely optional for the board. | Fixed, predictable, and legally mandated to be prioritised before equity shareholders. |
Missed Payout Status | Non-cumulative; skipped dividends are lost forever. | Accumulates as a balance sheet liability if issued as cumulative. |
Risk and Return Comparison Between Equity Vs Preference Shares
These two share types balance risk and return very differently.
With equity shares, the risk is the highest. If the business collapses and its assets are sold, equity investors are the last people waiting for a payout. Secured lenders are paid first. Bondholders come next. Preference shareholders follow. Whatever is left, if anything, goes to equity holders. Sometimes there is nothing left at all. That means a complete loss.
The upside tells a different story. There is no limit on how much equity investors can make. Their returns rise alongside the long-term success of the company.
Preference shares take a different path. They sacrifice unlimited growth for greater protection. Because they stand ahead of equity holders during liquidation, the chances of recovering the original investment are much better if the company closes.
There is a limit, though. Returns stop at the agreed coupon rate. Even if the company launches a life-changing product and profits explode, preference shareholders do not earn beyond that fixed amount.
Financial Metric | Equity Share Class | Preference Share Class |
|---|---|---|
Liquidation Seniority | Bottom priority; receives any remaining assets. after everyone else. | Higher priority; paid immediately after corporate bondholders. |
Maximum Upside Limit | Theoretically infinite; directly tracks long-term company growth. | Strictly capped at the pre-determined dividend percentage. |
Taxation of Equity Shares vs Preference Shares
Under current Indian tax laws, the fiscal treatment of your investment returns depends heavily on how long you hold the asset and how those payouts are distributed. Ever since the removal of the Dividend Distribution Tax (DDT), all dividends from both equity and preference shares are added to your total annual income and taxed directly at your regular progressive income tax slab rates.
However, when you sell these assets on the open market, the holding periods required to qualify for Long-Term Capital Gains (LTCG) tax treatment vary significantly. Listed equity shares face a much shorter timeline to qualify for favourable tax rates compared to unlisted preference instruments. The table below breaks down the current Indian domestic regulatory tax parameters across both asset classes.
Taxation Category | Listed Equity Shares | Unlisted Preference Shares |
|---|---|---|
Dividend Tax Treatment | Added to gross income; taxed at your regular tax slab rate. | Added to gross income; taxed at your regular tax slab rate. |
Long-Term Status Timeline | Achieved when the asset is held for more than 12 months. | Achieved when the asset is held for more than 24 months. |
Long-Term Capital Gains (LTCG) | Taxed flat at 12.5% on gains that exceed ₹1.25 Lakh. | Taxed flat at 12.5% under standard statutory rules. |
Short-Term Capital Gains (STCG) | Taxed flat at 20% under Section 111A regulations. | Added to total income; taxed according to your tax slab. |
Conclusion
Choosing between equity and preference shares is not about finding the better investment. It is about finding the one that matches your financial goals.
If you are comfortable with market fluctuations and are investing for long-term growth, equity shares may be a better fit. If you prefer relatively predictable income and priority over dividends, preference shares could make more sense.
Understanding the difference between equity share and preference share helps you make decisions that are based on your needs rather than assumptions.
The content in this blog is intended purely for educational purposes. Any securities or mutual funds referenced are illustrative in nature and do not constitute a recommendation or endorsement by Kotak Neo. Investors are encouraged to assess their own financial situation and seek professional advice before making any investment decisions. For compliance T&C and disclaimers, Visit https://www.kotakneo.com/disclaimer
0 people liked this article.
Vishwa has spent 10+ years across fintech and FMCG doing what most people miss, connecting the dots, catching trends before they trend, and finding the angle nobody else thought to ask about.
At Kotak Neo, she drives content strategy for neoshorts, Kotak News Desk, and Investing Guide, turning market noise into something worth reading.
When she's not decoding markets, she trades charts for canvases, chasing art, painting, and architecture across cities she's yet to explore.